Are We Going in Circles? What Circular Financing Really Means for the AI Trade

Markets have spent the back half of this year climbing on the back of an extraordinary AI infrastructure buildout — and for good reason. Hyperscaler capital spending is on pace to exceed $600 billion this year, with roughly three-quarters of it flowing into AI infrastructure: data centers, power capacity, and chips. But alongside the headline growth numbers, a quieter debate has moved from finance-Twitter skepticism into mainstream analyst reports: how much of that spending is genuine, dispersed end-market demand, and how much is a small cluster of companies financing each other and calling it revenue? Deal-tracking by analysts now puts the value of these interlocking arrangements — chipmakers investing in AI labs, AI labs committing to cloud providers, cloud providers buying chips to fulfill those commitments — north of $800 billion. The debate has a name: circular financing. And whatever side of it an investor lands on, the mechanics are worth understanding plainly, without the jargon that usually surrounds them.
Here's the easiest way to see it.
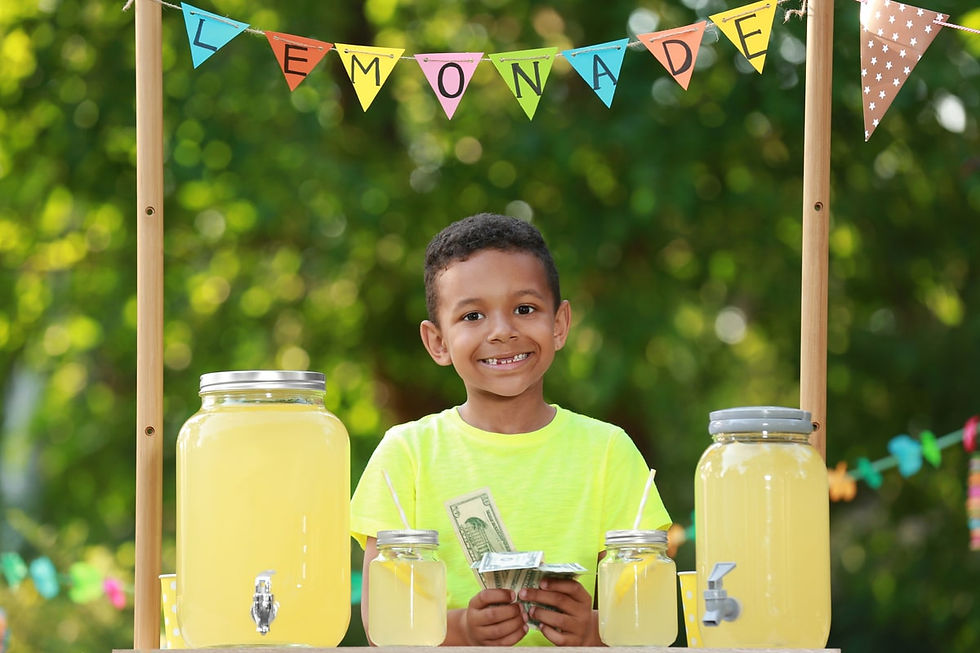
The Lemonade Stand Version
Imagine a kid — call her Vera — runs the only lemonade stand on the block. She also happens to be really good at building the wooden stands and juicers everyone else needs to open one.
The loop: Vera doesn't just sell juicers. She goes to three other kids — Otto, Corey, and Nia — and says: "Here's $10,000 to open your own lemonade stands. In exchange, I want equity, or I'll co-sign your loan." Otto, Corey, and Nia take the money and immediately spend most of it buying juicers and stands — from Vera. Vera books that as revenue. She now looks like she's running a booming juicer business with three thriving customers.
But trace the dollar: it started in Vera's pocket, went to Otto, and came right back to Vera. No lemonade was actually sold to a neighbor. No new demand for lemonade was created. The "revenue" is real in an accounting sense — the cash genuinely moved, invoices were genuinely paid — but it isn't evidence the neighborhood actually wants more lemonade. It's evidence that Vera is willing to fund her own customers.
Why people tolerate it: If Vera genuinely believes lemonade demand is about to explode — a heat wave is coming, a new subdivision is being built nearby — funding Otto, Corey, and Nia now so they're ready to serve that demand is a perfectly rational bet. This is the standard defense of vendor financing: the juicers are real, the stands get built, and if the heat wave comes, everyone wins. It's genuinely how a number of capital-intensive industries have been built historically — railroads, telecom fiber buildouts, and oil pipelines all went through vendor-financing waves that looked circular in the moment and, in some cases, turned out to be early rather than wrong.
Where it gets dangerous: Otto, Corey, and Nia don't have any lemonade customers of their own yet. Their only "revenue" is the equipment Vera funded them to buy from her. If the heat wave doesn't come — or arrives later than expected — Otto can't make his loan payment. He calls Corey, who co-signed part of the loan, and Corey can't cover it either, because he's in the same position. Vera now has to write down her equity stake in three kids who all owe money to each other and to her, simultaneously. One bad summer doesn't just dent Vera's juicer sales — it takes down the whole cluster, because Otto, Corey, and Nia were never really independent businesses. They were one balance sheet wearing four different t-shirts.
The Market's Current Question, In These Terms
Is the AI trade a genuine heat-wave bet — vendor financing bridging real, dispersed end-user demand that's about to materialize? Or is it four kids on the same block selling juicers to each other while nobody outside the block has bought a cup of lemonade yet?
The honest answer, at this point, is some of both. Real infrastructure is being built: concrete, power, and silicon that will exist regardless of how the financing questions resolve. At the same time, a meaningful share of reported demand traces back to a small number of firms that appear on multiple sides of the same deals — as investor, supplier, and customer at once. That concentration is what turns an ordinary financing question into a systemic one: it isn't about whether AI demand is real, it's about how much of the reported demand is the same capital circulating among a handful of counterparties, and what happens to all of them at once if growth comes in later or lighter than the deals assumed.
The variable worth watching isn't revenue growth — it's credit. A funding shortfall, a covenant breach, or a public reassurance from one counterparty about another's solvency is usually the first visible sign that a financing loop is under strain. Growth headlines can stay strong for a long time after the underlying demand has started to soften. Credit spreads and counterparty behavior tend not to.
Comments